Factual Lead
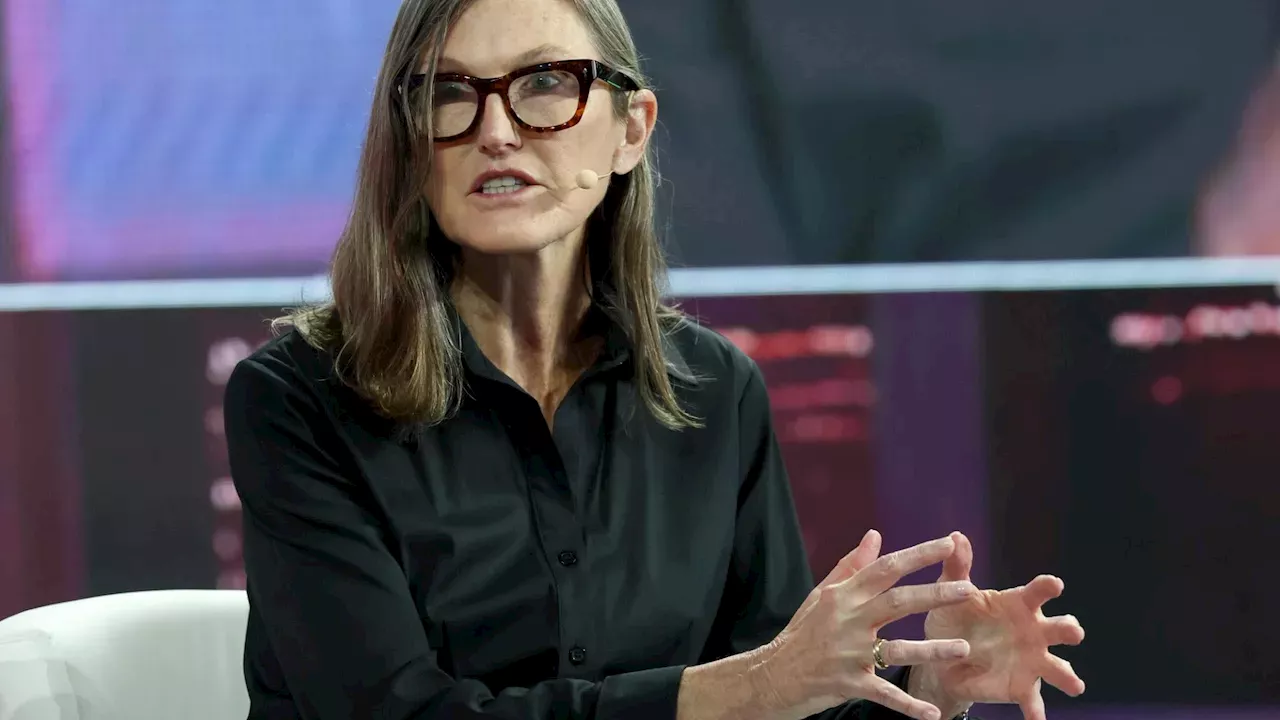
During a panel at Robinhood’s Summit in Houston on Wednesday, ARK Invest leader Cathie Wood stated that investors may need to shift focus toward how artificial intelligence software executes purchases. Wood noted that market participants should begin to “follow the agents” as software systems evolve from passive tools into active economic participants capable of spending real money and performing tasks independently.
What Changed
Artificial intelligence systems are rapidly moving past conversational response capabilities. Instead of merely answering questions or drafting text, modern software agents are beginning to take tangible actions, including purchasing digital services and managing commerce on behalf of users. According to industry experts, this transition creates a structural requirement for software to execute transactions directly, such as paying for an API call, buying data, or renting computing power without requiring a human to approve every individual micro-transaction.
This capability requires new mechanical frameworks for how machines handle currency. While traditional payment systems remain vital, software agents need high-speed, programmatic channels to settle exchanges instantly. Consequently, developers and financial institutions are racing to build automated payment systems tailored specifically to autonomous software.
Context and Infrastructure
To facilitate machine-to-machine commerce, technology companies and financial service providers are introducing dedicated transaction infrastructure. Coinbase has developed a system called x402, which is designed to let machines pay directly for online services such as data or API access.
At the same time, major mainstream financial and technology firms are building pathways for automated purchases. Companies including Stripe, Visa, Google, and OpenAI are actively developing methods that allow AI agents to make online payments. These initiatives highlight an emerging race to control the underlying rails that will power machine-driven transactions.
Concurrently, stablecoins and blockchain networks are emerging as alternative payment rails. Because stablecoins can move around the clock and blockchain protocols enable software to send micro-payments directly to other software, proponents argue these technologies are uniquely suited for machine economies.
Business Implications
The rise of autonomous software spending introduces critical business considerations regarding security, convenience, and financial control. Joseph Chalom, co-CEO of SharpLink and former head of digital assets at BlackRock, highlighted these stakes during a discussion last month, noting that “a world full of intelligent agents means nothing if a handful of companies decide where your money can go.”
Chalom argued that the financial systems utilized by AI agents should not be concentrated under the control of a small number of banks or technology platforms. He offered a practical use case where a human user authorizes an agent to spend up to $500 to book a hotel room, without granting the software unlimited access to their underlying bank account.
This dynamic creates a tension between centralized control and open networks. Whether agentic finance develops openly or becomes consolidated among major payment processors and tech platforms remains a central business uncertainty.
Sector Impact
The financial services and technology sectors are experiencing a direct collision as AI agents enter the economic sphere. Traditional payment heavyweights like Visa and Stripe are positioning themselves to capture automated transaction volume, while fintech and crypto innovators push for decentralized protocols.
BlackRock has explicitly stated that traditional payment systems will remain important, signaling that legacy financial institutions intend to maintain a central role in managing automated liquidity. Meanwhile, digital asset advocates argue that blockchain infrastructure is necessary to eliminate friction in high-frequency, low-value software transactions.
Limitations and Uncertainties
Significant questions remain regarding the long-term adoption and architecture of agentic commerce. Key uncertainties include whether agentic finance will develop primarily on open, blockchain-based networks or remain concentrated within proprietary systems managed by a small number of banks, payment providers, and technology platforms.
Additionally, it remains unclear whether crypto rails will capture meaningful market share for agent transactions or if the vast majority of agent activity will ultimately stay within traditional, fiat-based payment networks.
What to Watch Next
As software agents gain broader deployment, market observers should monitor several key developments:
- The adoption rates of specialized machine payment protocols like Coinbase’s x402.
- Product rollouts from major payment and technology firms including Stripe, Visa, Google, and OpenAI.
- Regulatory and institutional stances on stablecoin utility in automated transactions.
- User-permission models for bounding agent spending limits, such as capped hotel booking authorizations.