Introduction
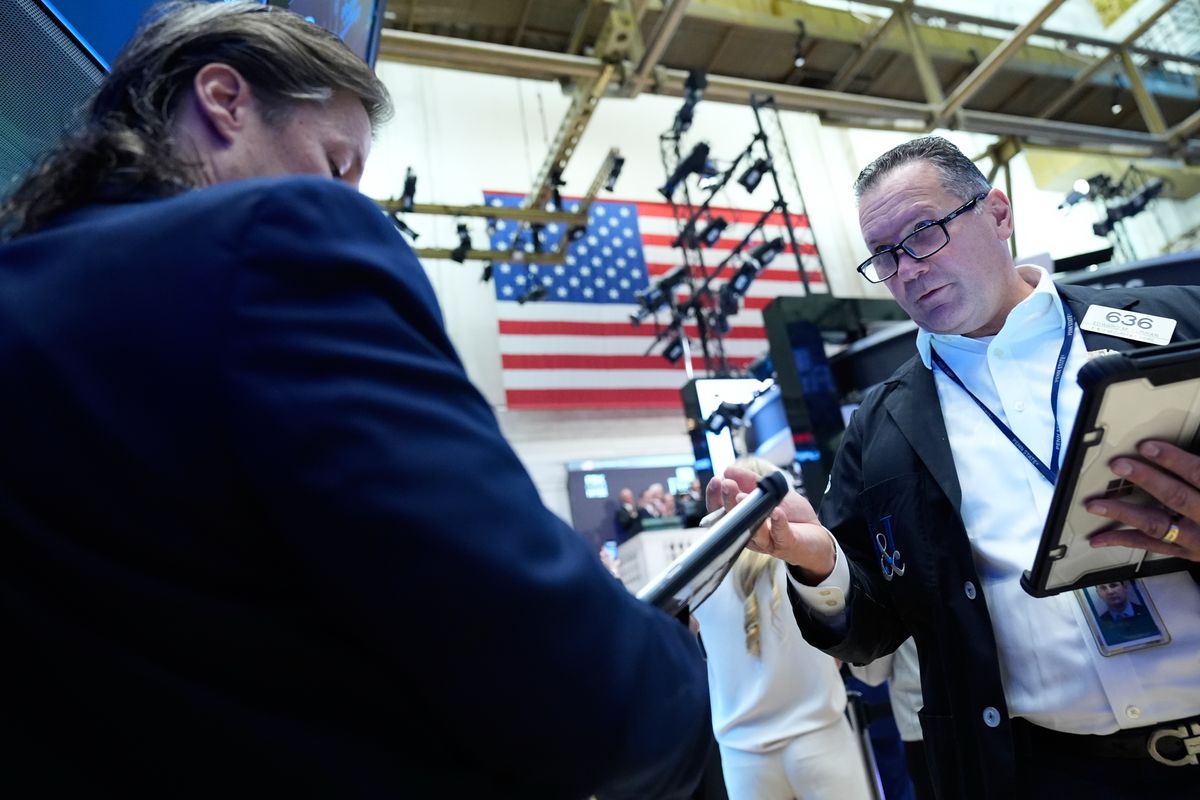
Wall Street enters a busy reporting cycle as financial markets prepare for a comprehensive series of economic updates. According to reports from AP News and Central Sierra Broadcasting Corporation, the upcoming schedule brings critical details regarding the Federal Reserve’s decision to raise interest rates at its most recent meeting. Beyond central bank policy discussions, market participants will review fresh performance data covering the health of the services sector, national unemployment levels, and consumer sentiment.
As investors navigate an environment marked by shifting economic signals, these scheduled releases provide vital visibility. Analysts and economists rely on these updates to measure how both commercial enterprises and everyday households are adapting to persistently high inflation and evolving borrowing costs.
What Changed
The financial calendar introduces a sequenced rollout of high-impact macroeconomic data points spanning from Monday through Friday. On Monday, the Institute for Supply Management kicks off the reporting week by releasing its monthly service sector index for September. Because the services sector accounts for the bulk of overall United States economic activity, this index serves as an essential barometer for broader commercial health.
Midweek action shifts to monetary policy when Wall Street receives the official Federal Reserve meeting minutes on Wednesday. These documents reveal the internal decision-making process behind the central bank’s recent choice to raise interest rates. Moving into the latter half of the week, Thursday brings the routine weekly update on unemployment claims. These figures remain historically low and function as a direct proxy for tracking corporate layoffs. Finally, the University of Michigan concludes the economic calendar on Friday by releasing its preliminary consumer sentiment survey for October.
Context and Background
To understand the weight of this week’s scheduled disclosures, observers must look at the prevailing macroeconomic climate. The Federal Reserve continues to manage monetary policy in an environment where inflation remains stubbornly high. Central bank officials have utilized interest rate increases as a primary tool to cool demand and stabilize prices, making every detail from past policy meetings subject to intense scrutiny.
Concurrently, previous reporting provides necessary baseline context. The September consumer sentiment survey from the University of Michigan highlighted clear vulnerabilities among everyday Americans. Specifically, households expressed growing concerns regarding rising fuel prices and stubbornly high inflation. The upcoming October survey will test whether those anxieties have intensified, eased, or stabilized.
Why It Matters
Reports covering services, employment, and consumer sentiment collectively offer investors and economists deep insight into the resilience of the U.S. economy. Financial markets react dynamically to any divergence between macroeconomic reality and analyst expectations. When the Institute for Supply Management publishes its service sector index, investors look for signs of sustained expansion or contraction in consumer-facing and business-to-business services.
Similarly, the weekly unemployment claims update remains a vital early warning indicator. Because these figures track ongoing layoffs in near-real-time, any unexpected shifts can rapidly alter trading sentiment. Furthermore, understanding consumer sentiment helps businesses project future spending patterns, bridging the gap between hard macroeconomic data and everyday purchasing behavior.
Business Implications
For corporate leadership and financial institutions, the incoming data directly informs operational and strategic planning. The Federal Reserve meeting minutes carry substantial weight for corporate borrowing costs, capital expenditure planning, and debt refinancing strategies. If the minutes suggest that policymakers view current interest rate levels as sufficient, businesses may find more predictability in credit markets.
Conversely, indications of prolonged monetary tightening could prompt firms to reevaluate expansion plans, hiring targets, and inventory management. Retailers and consumer goods companies will monitor the University of Michigan consumer sentiment survey closely, as shifts in household confidence directly correlate with discretionary spending and quarterly earnings performance.
Risks and Limitations
While economic updates provide essential transparency, market participants must navigate inherent limitations and uncertainties. The exact details of what the Fed minutes will reveal about the central bank’s internal debates regarding inflation and the job market remain prospective until official publication.
Furthermore, preliminary survey data, such as the University of Michigan’s consumer sentiment index, is subject to subsequent revisions as more responses are tabulated and analyzed. Relying on single-week metrics like unemployment claims also requires caution, as seasonal factors and administrative anomalies can cause short-term volatility that does not reflect structural economic trends.
What to Watch Next
As the week unfolds, financial analysts will synthesize each data release to update their macroeconomic forecasts. Observers should track how the Institute for Supply Management’s service sector index compares against historical averages, monitor the tone of the Federal Reserve meeting minutes for clues regarding future policy paths, and evaluate the trajectory of weekly unemployment claims against baseline historical lows. The culmination of these metrics on Friday with the consumer sentiment update will provide a comprehensive snapshot of economic momentum as the fourth quarter begins.