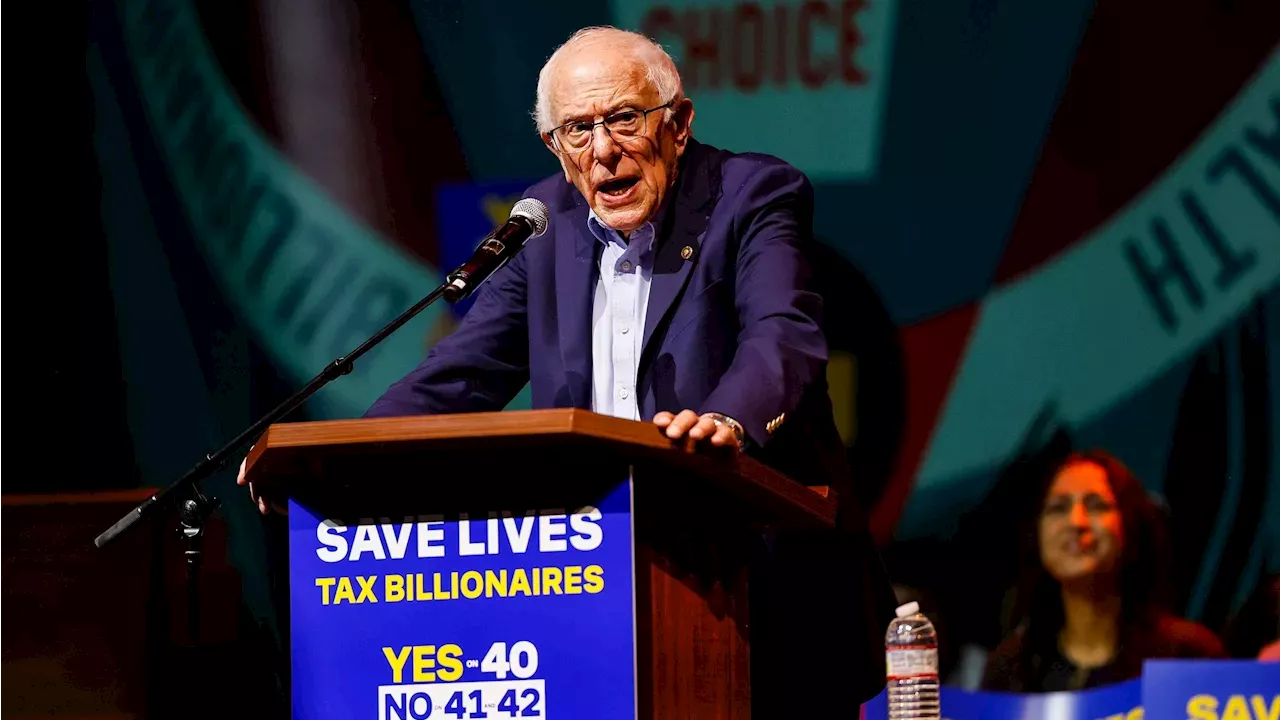
A letter signed by Nobel Prize winners recently defended California’s Prop. 40, describing it as “the first-ever tax on billionaire wealth enacted anywhere in the world.” However, despite this academic backing, the controversial levy faces severe hurdles, including administrative challenges, potential unconstitutionality, and significant capital flight before its effective date.
What Changed
California advanced Prop. 40, introducing a wealth tax structure aimed directly at the state’s ultra-wealthy residents. In an effort to bolster public support, a group of Nobel Prize winners signed a letter defending the policy. The signatories argued that the measure would help offset “massive funding cuts” to California’s Medicaid program and claimed that local billionaires paid income tax equal to just 1.6% of their wealth gains.
Despite this high-profile advocacy, the measure confronts immediate operational and structural pushback. Governments have taxed net wealth for decades, starting in the 1990s in Europe, but most of those historical European wealth taxes were eventually repealed. Critics note those programs raised little revenue, proved costly to administer, pushed investment out of those regions, and remained deeply unpopular with the public.
Context and Historical Precedent
The debate over Prop. 40 arrives against a backdrop of prior global wealth tax experiments. European nations attempted similar measures during the 1990s, only to abandon them due to administrative drag and capital flight.
Proponents of the California measure point to the 1.6% figure as evidence of an unfair tax burden, asserting that billionaires pay minimal income tax relative to their overall wealth gains. Analysts point out that this calculation is misleading because the 1.6% metric divides income taxes paid by an increase in estimated asset values, much of which remains unrealized.
Furthermore, the Nobel laureates’ letter claimed Prop. 40 would prevent massive funding cuts to Medicaid. Research notes, however, that these specific funding adjustments achieve savings by adding work or volunteer requirements. Additionally, federal spending on Medi-Cal is projected to be 50% higher in 2034 than it was in 2019.
Business Implications and Capital Flight
The most immediate business impact of Prop. 40 involves the relocation of prominent executives, founders, and investors. Prominent figures—including Sergey Brin, Larry Page, Peter Thiel, Don Hankey, Travis Kalanick, Steven Spielberg, and David Sacks—reportedly left California ahead of the Jan. 1, 2026, effective date of the tax. For context, Larry Page previously secured New Zealand residency, as confirmed by officials on Friday, Aug. 6, 2021.
Stanford researchers Joshua Rauh and Benjamin Jaros investigated the pre-effective migration patterns and found that nearly 30% of the expected taxable wealth left California before the measure even qualified for the ballot. This substantial outflow directly shrinks the intended tax base before the policy can generate funds.
Revenue Projections and Economic Impact
Proponents initially promised that the tax would pull in $100 billion in new tax receipts. Reality, however, looks markedly different according to official state projections. California’s nonpartisan Legislative Analyst’s Office estimates the tax could raise “tens of billions” rather than the originally promised $100 billion.
Economic models suggest that rising billionaire wealth is not evidence that anyone else has been made poorer. Instead, the likeliest result of Prop. 40 is a smaller tax base and a higher tax bill falling on everyone who stays in the state.
Risks, Limitations, and Constitutional Uncertainty
Legal and structural risks further complicate the implementation of Prop. 40. Observers note that Prop. 40 could be unconstitutional in as many as unspecified areas, and taxpayers are expected to dispute the tax’s legality in court.
While some commentary suggested that it is unlikely any significant number of billionaires successfully cut ties with the Golden State, empirical migration data compiled by Stanford researchers shows a massive early departure of taxable assets. Administrative overhead, combined with ongoing litigation over asset valuations and constitutional compliance, threatens to bog down the state’s tax collection efforts.
What to Watch Next
As the Jan. 1, 2026, effective date approaches and subsequent legal challenges unfold, observers will monitor how California addresses its shrinking tax base. Key indicators to watch include formal court filings challenging the constitutionality of the wealth tax, updated revenue forecasts from the Legislative Analyst’s Office, and further migration trends among high-net-worth individuals.