What Changed in the Housing Market
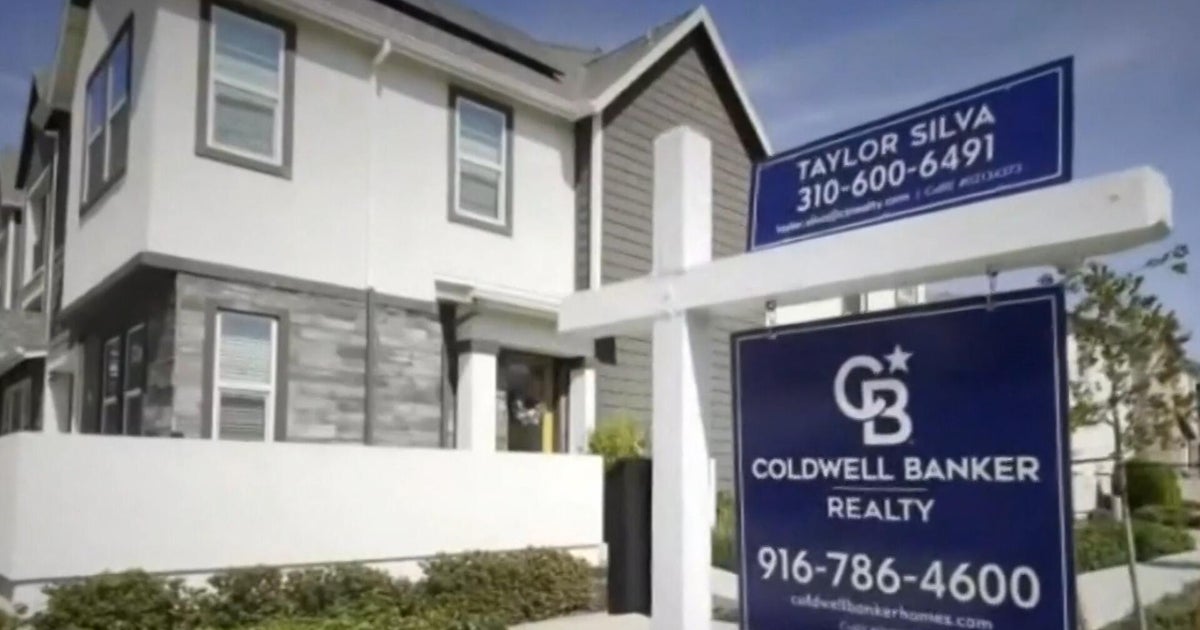
Mortgage rates have escalated to three-year highs, exerting direct downward pressure on transaction volumes and cooling buyer activity across the market. The milestone marks a critical inflection point for the residential property sector, reversing momentum from prior low-rate environments and directly dampening consumer purchasing power.
The development was reported by Akiko Fujita for CBS News, delivering on-the-ground reporting from Los Angeles on Oct 5. The segment detailed how elevated financing expenses are actively pushing down housing sales as prospective purchasers recalibrate their budgets against sharply higher monthly debt obligations.
Reporting Details and Overview
According to the Oct 5 CBS News broadcast filed from Los Angeles by Akiko Fujita, the ascent of mortgage rates to levels not recorded in three years has altered market conditions. A summary of the key reporting facts includes:
- Benchmark Movement: Mortgage rates have established fresh three-year highs.
- Market Response: Higher mortgage rates are directly pushing down housing sales.
- Reporting Origin: Coverage filed from Los Angeles by reporter Akiko Fujita for CBS News.
- Coverage Timing: Broadcast released on Oct 5 spanning a 01:51 video report.
The Economic Mechanism: How Higher Borrowing Costs Suppress Sales
The relationship between borrowing benchmarks and property turnover is direct. When mortgage rates advance to three-year highs, the cost structure of real estate acquisition changes immediately for debt-reliant buyers.
Diminished Purchasing Power
Real estate transactions depend heavily on long-term amortized debt. When mortgage rates escalate to multi-year peaks, the interest component of each scheduled payment increases. For a household working with a fixed monthly housing allowance, higher rates shrink the principal loan amount they can service. As purchasing power contracts, potential buyers are forced either to lower their price horizons or exit the market entirely, driving down total housing sales.
The Seller Hesitation and Inventory Squeeze
Higher rates also influence existing property owners. Homeowners who secured long-term financing during previous years when rates were substantially lower face a financial disincentive to sell. Relocating or upsizing requires relinquishing a favorable rate in exchange for borrowing at three-year highs. This dynamic reduces the willingness of homeowners to list properties, dampening transaction counts from both the supply and demand sides.
Sector Impact: Real Estate and Lending
The transmission of three-year high mortgage rates spreads across multiple interrelated sectors within the broader economy.
Residential Brokerages
Real estate agencies and brokerage firms rely directly on transaction velocity for commission revenues. When elevated mortgage rates push down housing sales, deal volume declines. Brokerages must navigate elongated listing periods, increased rate sensitivity during negotiations, and a reduced pool of pre-qualified buyers.
Mortgage Origination and Lending Services
For mortgage banks, independent lenders, and credit unions, higher rates constrain both purchase-money originations and refinancing operations. With interest rates sitting at three-year highs, refinance demand drops significantly because existing borrowers have little incentive to replace older loans. At the same time, the decline in housing sales limits new purchase origination volume, forcing lending businesses to adjust operational overhead.
Ancillary Real Estate Services
A slowdown in transaction activity extends into title insurance, property appraisals, escrow services, and home inspection businesses. These service providers generate revenue per transaction; as fewer sales close, aggregate operational activity across these segments softens in tandem.
Business Implications for Market Participants
The transition to three-year high borrowing costs introduces specific business realities across different segments of the market ecosystem.
Homebuyers
Buyers in the market face strict underwriting scrutiny. Higher mortgage rates require greater income thresholds to satisfy debt-to-income (DTI) requirements. Buyers who remain active must evaluate their down payment reserves, reassess property choices, and balance the risk of carrying higher ongoing interest obligations.
Home Sellers
Sellers accustomed to rapid sales cycles must adapt to shifting conditions. With fewer qualified buyers competing for available stock, properties may stay on the market longer. Sellers may face pressure to adjust list prices or provide financial concessions to offset elevated mortgage rates for hesitant purchasers.
Homebuilders and Developers
Residential development firms face changing economics. Elevated borrowing costs not only raise interim construction loan expenses but also restrict the eventual buyer pool for finished units. Builders must monitor consumer rate sensitivity carefully to avoid carrying unsold inventory across extended market cycles.
Risks and Market Limitations
The ongoing pressure exerted by high borrowing costs introduces key operational and financial risks:
- Affordability Compression: The rapid climb to three-year highs disproportionately affects first-time buyers who lack existing home equity to subsidize a down payment.
- Transaction Stagnation: If buyers cannot qualify and sellers refuse to adjust pricing or sacrifice low-rate legacy loans, the overall marketplace experiences transaction paralysis.
- Economic Multiplier Contraction: Housing turnover drives substantial downstream economic activity, including home improvements, furnishings, and moving services. Depressed sales suppress these secondary revenue streams.
Limitations of the Available Reporting
While the Oct 5 CBS News broadcast confirms that mortgage rates have climbed to three-year highs and are dampening housing sales, several specific details were outside the immediate factual scope of the brief:
- The exact numerical percentage of current mortgage rates and the precise baseline rate from three years prior were not specified in the initial factual brief.
- Specific national, regional, or local percentage declines in transaction volume were not quantified.
- Future monetary policy determinations and long-term interest rate projections were not established within the report.
What to Watch Next
Market observers, lenders, and prospective buyers tracking the fallout from these three-year highs should monitor key business and structural signals:
- Lending Benchmarks: Track whether mortgage rates stabilize, retreat, or push past their current three-year highs in upcoming reporting periods.
- Transaction Velocity: Observe regional housing sales metrics to determine whether transaction declines remain broad or concentrate in high-cost metro areas like Los Angeles.
- Pricing Adjustments: Follow listing inventory data to see if persistent sales declines prompt broader list-price corrections from property sellers.
- Origination Volume: Review quarterly operational reports from primary mortgage originators to measure the ongoing business impact on lending capacity.